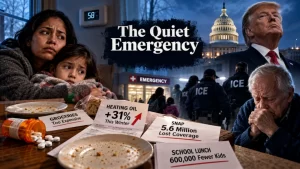
Open enrollment for 2027 coverage began this weekend into a market that is shrinking, sicker and more expensive by design. Premiums are climbing by double digits for a second straight year, millions have already been priced out, and new restrictions take effect in January. The president who promised to replace Obamacare in three campaigns has delivered $500 checks to a fraction of enrollees on the eve of an election — and nothing that resembles a plan.
Yesterday, on a quiet Sunday, the doors of HealthCare.gov swung open for another year. For the roughly twenty million Americans who buy their own insurance — the gig workers, small-business owners, farmers, early retirees and self-employed who keep this economy running — the annual ritual of shopping for coverage began. According to healthinsurance.org, most people have until December 15 to pick a plan that starts January 1, and until January 15 to enroll at all. What they will find when they log in is the second consecutive year of sticker shock, fewer insurers, less help, and a federal government that has decided their problem is not its problem.
This is not a natural disaster. It is a policy choice — made by a Republican Congress that let the enhanced premium tax credits lapse at the end of 2025, and by a president who has spent a decade promising Americans “something terrific” while delivering something considerably worse. Tomorrow, voters get their say.
I. The Bill Comes Due — Again
The numbers released last week by KFF are stark. The average finalized benchmark silver premium is rising 13% for 2027, on top of a 26% jump the year before — a cumulative increase of about 42% in just two years. Premiums in states using HealthCare.gov are up 11%; in states running their own exchanges, 16%. KFF’s analysts note that insurers explicitly blamed the expiration of the enhanced tax credits, and the resulting exodus of healthier customers, for roughly four percentage points of last year’s increase — and they expect a similar additional hit this year.
For subsidized enrollees, the underlying premium matters less than what comes out of their own pocket. And on that score, 2026 was brutal. KFF found that enrollees faced an average increase of 114% — more than $1,000 a year — in what they paid to keep the same plan. Many responded the only way they could: by fleeing to cheaper bronze plans with towering deductibles. The average Marketplace deductible grew by about $1,000 per person in 2026, and the share of enrollees in bronze plans jumped from 30% to 40%, as AJMC reported. That is not “coverage” in any meaningful sense for a family that cannot afford to meet its deductible. It is a bet that nothing goes wrong.
Those hit hardest are middle-income Americans earning more than 400% of the poverty line — about $63,840 for a single person. With the enhanced credits gone, they have no federal assistance at all and must pay full price — and KFF warns these sharp increases may push more healthy enrollees out, worsening the risk pool further. This is the “subsidy cliff” the 2021 reforms erased, and that Republicans chose to restore.
Premiums, 2025–2027
Average benchmark silver premiums have risen 42% over two years, with a 13% increase for 2027 following 26% last year. KFF
Coverage Lost
Families USA counts more than five million people who lost Marketplace coverage in 2026 after the credits expired, including nearly 4 million who signed up but never paid a first premium. Families USA
CBO Projection
The Congressional Budget Office projects Marketplace enrollment will fall from a 22.4 million peak in 2025 to 13.1 million in 2027. KFF / CBO
Insurers Leaving
Eleven carriers announced exits from at least one state for 2027 versus seven entries. Cigna is leaving the individual market in all 11 of its states. KFF
Out-of-Pocket Shock
The average Marketplace deductible rose about $1,000 per person in 2026 as enrollees were pushed into high-deductible bronze plans. KFF
The Only Exception
Enrollment fell in every state except New Mexico — the only state that fully replaced the lost federal credits with its own money. KFF
II. What’s New — and Worse — for 2027
As if higher prices were not enough, January 1 brings a fresh round of restrictions from the Republican reconciliation law Trump branded the “One Big Beautiful Bill.” KFF’s guide lays them out plainly:
Uncapped clawbacks. Beginning with the 2026 tax year, the law eliminated the limits on how much enrollees must repay if their income ends up higher than they estimated. Because the first returns under the new rules won’t be filed until early 2027, families are choosing 2027 plans without ever having seen how punishing these bills can be. A freelancer who lands one good contract late in the year could owe thousands back to the IRS.
Refugees and asylees cut off. Lawfully present immigrants — including refugees, asylees and survivors of human trafficking — can still buy coverage but will no longer qualify for premium tax credits. The CBO estimates this single provision leaves one million more people uninsured by 2035.
Medicaid work requirements reach the Marketplace. The law requires 43 states and D.C. to implement Medicaid work requirements by the start of 2027. Anyone who loses Medicaid solely for failing to meet them — including working people tripped up by paperwork — will also be barred from subsidized Marketplace coverage. The safety net now has a trapdoor.
Less help navigating it all. The administration slashed Navigator funding by 90% and, in September, froze registration of new agents and brokers on the federal platform until February 2027 — blocking an estimated 19,000 new brokers. The same month, HHS cancelled coverage for roughly 760,000 people it labeled “phantom” enrollees; KFF notes reports that some legitimate enrollees were swept up and later had to be reinstated.
One piece of good news came not from Washington’s political branches but from the courts. A federal judge vacated the administration’s rule that would have cut open enrollment short at December 15, preserving the January 15 deadline for this cycle. HHS has appealed.
III. Three Campaigns, Zero Plans
Donald Trump has now run for president three times on the promise of replacing the Affordable Care Act. As Axios documented, he vowed as early as 2015 to repeal it and “replace with something terrific.” In 2019 he promised a plan that would blow Obamacare away — after the next election. In 2020 he insisted a full plan would be signed within two weeks. It never was. His one serious attempt, the 2017 American Health Care Act, would have knocked millions off coverage and died in a Republican Senate.
Then came the 2024 debate in Philadelphia, when ABC’s Linsey Davis asked a simple yes-or-no question: did he have a plan?
“I have concepts of a plan.”
— Donald Trump, presidential debate, Sept. 10, 2024 · via Mother Jones
He said Americans would hear about it in the not-too-distant future. Nearly two years into his second term, what they got was the “Great Healthcare Plan,” released on January 15, 2026 — the very day open enrollment closed in most states. The Washington Post reported that it fell far short of Trump’s promise to deliver an ACA replacement. NBC News found it lacked key details and largely restated ideas the president had floated before. The White House fact sheet describes funding cost-sharing reductions, publishing insurers’ claim-denial rates and sending subsidy money “directly to the people” — a rough sketch of health-savings-account deposits. CMS Administrator Dr. Mehmet Oz called it a framework for lawmakers to build on. The nonpartisan Committee for a Responsible Federal Budget noted the core subsidy idea could substantially increase borrowing depending on how it was designed — because it was not, in fact, designed.
Senator Ron Wyden of Oregon, the top Democrat on the Finance Committee, dismissed it as more of Trump’s “empty promises”. Ten months later, there is no bill. There is no CBO score. There is no vote. After a decade, the concepts remain concepts.
IV. How Congress Let It Happen
The road to this open enrollment season runs through a series of choices — each documented, each avoidable.
The irony of December’s Senate debate is hard to miss. Rejecting the Democrats’ extension, Thune scoffed that a simple renewal of the credits wasn’t a real plan, telling colleagues he didn’t know how anyone could “call it a plan”. That from the party whose president was still offering concepts.
The House vote proved a bipartisan majority existed in that chamber. Anthony Wright of Families USA said at the time that majorities in both chambers now supported stopping the premium spikes. What stood in the way was leadership — and a White House that never put its weight behind a fix. When the Moreno-Collins talks finally fell apart, the Ohio senator was blunt:
“It’s effectively over.”
— Sen. Bernie Moreno (R-Ohio), on the bipartisan ACA talks, Feb. 2026 · via The Hill / WSJ reporting
V. A Shrinking Market Raises Everyone’s Bill
If you get insurance through your job, you may think this is someone else’s crisis. It isn’t. Georgetown law professor Lawrence Gostin told Healio that one overwhelming reason explains the enrollment drop: the premium spike caused by the credits’ expiration. And when people drop coverage, they don’t stop getting sick.
The dynamic is well understood. Younger, healthier people leave first — exactly what insurers predicted in their filings, according to KFF. The remaining pool gets older and sicker, premiums rise again, more people leave. Meanwhile, the newly uninsured still show up in emergency rooms. The Urban Institute projected 4.8 million more uninsured Americans in 2026 alone. A separate Healio report cited analyst estimates of a $7.7 billion surge in uncompensated care in 2026 and $32.1 billion in lost revenue for providers — a blow that falls hardest on rural and safety-net hospitals already operating on thin margins.
That money doesn’t vanish. Georgetown’s Sabrina Corlette explained to Marketplace that as hospitals’ uncompensated care costs climb, those costs have to be passed on — to employers, to workers in employer plans, and to taxpayers. Letting the credits expire saved the federal government money on paper. In practice, it moved the bill from the Treasury to your paycheck, your local hospital and your county budget.
Get Involved Today
Contribute to our mission and turn your concerns into action.
VI. What the President Has Actually Done
Measure Trump not by his promises but by his record on health coverage this term:
He signed the cuts. The reconciliation law he championed didn’t address the expiring credits, as KFF notes — it instead imposed Medicaid work requirements, stripped tax credits from refugees and asylees, and uncapped IRS clawbacks for working families.
He opposed the fix. He refused to back the House-passed extension and floated a veto. His own “plan” remains a press release.
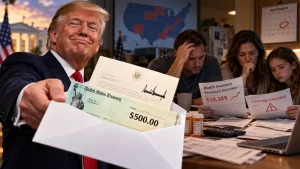
He mailed checks before an election. On September 10, the White House announced “Working Families Obamacare Refunds” — $500 per person to nearly one million unsubsidized enrollees in 30 HealthCare.gov states, paid from surplus exchange user fees and framed as returning “Biden overcharges.” PolitiFact counted it among a trio of payments Trump promised in the final stretch before the midterms, alongside $90 for some Medicare enrollees. MIT economist Jonathan Gruber, one of the ACA’s architects, called the framing a “misleading claim” and argued to Newsweek that the program was really about the congressional elections. Recipients get letters signed by Trump. Consider the arithmetic: a one-time $500 check, roughly $500 million in total, against a 114% average increase in premium payments for millions and the loss of coverage for more than five million people.
That is what this White House’s priorities look like in practice: a branded rebate for some, a closed door for many more, and a camera-ready announcement in place of governing.
Who Holds the Power — and Who Answers for How It’s Used
The premium tax credit is a creature of statute, not executive grace. Its architecture tells us exactly where accountability lies.
- 26 U.S.C. § 36B — The ACA’s premium tax credit remains law. The “enhanced” version, enacted in the 2021 American Rescue Plan and extended through 2025, simply lapsed when Congress declined to renew it. No court, agency or president ended it; congressional inaction did.
- Article I, Section 8 & 9 — the Power of the Purse. Only Congress can authorize the spending needed to restore the credits. That is why the House’s 230–196 vote mattered, and why the Senate leadership’s refusal to schedule it is a deliberate exercise of that power — and a choice voters can hold them to.
- Article II, Section 3 — the Take Care Clause obligates the president to faithfully execute the laws, including the ACA as written. Administrative rules that narrowed enrollment, gutted Navigator assistance and shortened the enrollment window have repeatedly run into the courts: in City of Columbus v. Kennedy and California v. Kennedy, judges stayed or vacated key provisions, as KFF details.
- Public Law 119-21 (the 2025 reconciliation law) — Sections governing immigrant eligibility (§ 71301) and recapture of excess credits (§ 71305), plus the Medicaid work requirement provisions, were enacted by Congress and signed by the president. What Congress did, Congress can undo — but only with a Senate that will vote and a president who will sign.
The constitutional lesson is plain: this is not a crisis of capacity. It is a crisis of will, located precisely in the institutions the Constitution makes answerable at the ballot box.
VII. What Democrats Say They’ll Do
Democrats have made health care the centerpiece of their closing argument. House Democratic Leader Hakeem Jeffries, in line to become Speaker if his party wins tomorrow, said Democrats would be united “right out of the gate” on reinstating the ACA tax credits and reversing the Republican Medicaid cuts. According to PBS NewsHour, Jeffries created five affordability working groups months ago, with Rep. Terri Sewell of Alabama leading health care. NBC News reports the plan unfolds in three tranches: the first 100 hours, the first 100 days, and the first year. The Washington Times reports Democrats now intend to make the enhanced credits permanent rather than temporary.
Not everyone thinks that goes far enough. Rep. Alexandria Ocasio-Cortez told NBC that restoring the Medicaid and ACA funding would “absolutely not” be enough, calling for confrontation with Big Pharma, insurers and private equity. Rep. Brendan Boyle, in line to chair the Budget Committee, has pledged immediate action, per The Hill.
Honesty requires acknowledging the obstacle. As The Hill notes, even a Democratic sweep would leave Trump in the White House with a veto pen, and the Senate filibuster would still demand 60 votes. A Democratic House alone can pass bills, force votes, and conduct oversight of the administration’s enrollment purges — but it cannot sign legislation into law. What a new majority can do is put every member of Congress on the record, again, and make the 2027 open enrollment season the last one conducted without a fight.
VIII. What You Can Do
Nothing Congress does this week will change the prices on your screen. Here is how to protect yourself and your family right now — and how to change the outcome for next year.
No federal relief will arrive before 2027 coverage begins. The best tools available are careful shopping, accurate income estimates, state-level programs, and pressure on the officials who can change the law. Each option below is real; none is a substitute for Congress acting.
Actively shop — don’t auto-renew
With 11 insurers exiting markets and Cigna leaving the individual market entirely, your current plan may be gone or more expensive. Compare every option on HealthCare.gov or your state exchange before December 15 for January 1 coverage. Look past the monthly premium to the deductible and out-of-pocket maximum.
Estimate your 2027 income carefully
The repayment caps are gone. If your income could rise, estimate conservatively and update the Marketplace mid-year if your circumstances change. KFF notes that contributions to an HSA or traditional IRA can lower your counted income and may increase your credit or keep you eligible for cost-sharing reductions near 250% of poverty.
Check for state help
New Mexico fully replaced the lost federal credits; California expanded its program to households between 165% and 200% of poverty; New Jersey continues its subsidies; and Rhode Island and Virginia created new ones for 2027, per KFF. If you live in a state-run exchange, look for these programs explicitly.
Get free, legitimate help — and avoid junk plans
Use the official “Find Local Help” tool on HealthCare.gov. Be wary of anyone promising guaranteed zero-dollar premiums or cash to enroll — the new federal rules prohibit those tactics. Avoid short-term plans: as KFF explains, they can reject you for pre-existing conditions and don’t qualify for any tax credits.
Vote tomorrow — and keep the pressure on after
Election Day is Tuesday, November 3. Find your polling place through your state’s official election site. Then call your senators at the Capitol switchboard (202-224-3121) and ask one question: will they vote to restore the ACA tax credits in January? Write down the answer. Share your premium notice with your local paper and your representatives — real numbers move lawmakers more than talking points.
Editorial Conclusion
For ten years, Donald Trump has promised Americans a better, cheaper health plan. What he has delivered is higher premiums, fewer insurers, less help, uncapped tax bills for working families, millions of people pushed out of coverage — and a $500 check with his signature on it, mailed weeks before an election.
This was a choice. The House voted to fix it. The Senate’s leadership refused, and the president never asked them to. Health security is not a favor dispensed by a president; it is a law written by Congress, and the people who write it answer to us. Tomorrow, the American people get to decide whether this choice stands. A democracy that cannot keep its citizens insured is failing at its most basic promise — and it is time to elect a Congress that will keep it.
Sources & References
- KFF — 9 Things to Watch for the 2027 ACA Open Enrollment Period (Oct. 30, 2026)
- KFF — Midterm Election Update: The Affordable Care Act Marketplaces
- KFF — What We Know So Far About 2026 ACA Marketplace Enrollment, Premiums, and Deductibles
- KFF — How Has ACA Marketplace Enrollment Changed Across States in 2026?
- Families USA — Demographics of the More Than Five Million Americans Who Dropped Marketplace Coverage
- healthinsurance.org — What Are the Deadlines for the ACA’s Open Enrollment Period?
- AJMC — ACA Marketplace Enrollment and Affordability Take Historic Hit
- Axios — Trump’s Undelivered Health Care Plan (Sept. 12, 2024)
- Mother Jones — After a Decade, Trump’s Health Care Plan Still in “Concept” Phase
- The Washington Post — Trump Launches “Great Healthcare Plan,” Touting Grab Bag of Initiatives
- NBC News — Trump Announces Health Care Plan, but It Needs Congress’ Approval
- The White House — Fact Sheet: Trump Calls on Congress to Enact the Great Healthcare Plan
- Committee for a Responsible Federal Budget — White House Releases “Great Healthcare Plan”
- The Daily Record / Reuters — Trump Unveils Health Care Plan Featuring Direct Payments
- The White House — Fact Sheet: Working Families Obamacare Refunds (Sept. 10, 2026)
- Newsweek — Obamacare $500 Refund Checks Are Here
- PolitiFact — Trump Promised a Trio of Payouts to Americans
- Axios — Dems Accept Shutdown Deal Without ACA Guarantee
- AJMC — Bills to Address Expiring ACA Subsidies Fail to Pass Senate (Dec. 11, 2025)
- Healthcare Innovation — House Passes ACA Healthcare Subsidies Extension
- Common Dreams — Senate Slammed for Punting on Bill to Restore ACA Subsidies
- ACASignups.net — ACA Subsidy Negotiations Appear to Be Dead
- Word & Brown / The Hill — Senate Talks to Revive ACA Tax Credits Appear to Be Fizzling Out
- The Philadelphia Inquirer / AP — House Democrats Plan Agenda for First 100 Days
- PBS NewsHour — What’s on House Democrats’ Agenda If They Sweep to Power
- NBC News — Healthcare Tops the Democrats’ To-Do List
- The Hill — Democrats, With House Majority, Would Go Big on Healthcare
- The Washington Times — Democrats Ready to Spend More on Obamacare If They Win Control
- Healio — ACA Enrollment Plummets With Enhanced Premium Tax Credit Expiration
- Marketplace — Millions Could Drop ACA Coverage This Year, Pushing Premiums Up
- Urban Institute — 4.8 Million People Will Lose Coverage in 2026 If Enhanced PTCs Expire
- KFF — A 90% Cut to the ACA Navigator Program
Related News